Britvex: HMRC-Supervised Accounting Support for UK Contractors and Technical Businesses
BRITVEX ADVISORY · UK PROFESSIONAL CREDENTIALS & SERVICE CONTROLS
Britvex: HMRC-Supervised Accounting Support for UK Contractors and Technical Businesses
A construction or technical contractor should not have to reconstruct payroll, CIS, materials, VAT and job margins from different systems at year end. The underlying records need to connect.
Editorial perspective by Syed Raheel Shahzad · Founder & Group CEO, The Syed Group
Companies House ACSP registration · HMRC AML supervised (reference XNML00000219568) · HMRC Agent Services Account · ICO registration ZA013667080.
These credentials identify distinct regulatory or administrative responsibilities. Neither Companies House ACSP registration nor HMRC AML supervision constitutes government endorsement of accounting advice.
Contractor accounting begins with the job, not the bank statement
A technical installation or construction project generates more than one payment. Materials, subcontractors, labour, variation orders, retention amounts, deposits and completion milestones can all affect the financial result. When these are coded only as generic expenses, the contractor loses sight of project margin and cash needs. Britvex's contractor and construction accounting approach can help connect the job cycle to the accounting ledger. The records should identify work performed, costs incurred, invoiced amounts and cash settlement so that managers can understand both profitability and timing.
CIS responsibilities require correct classification
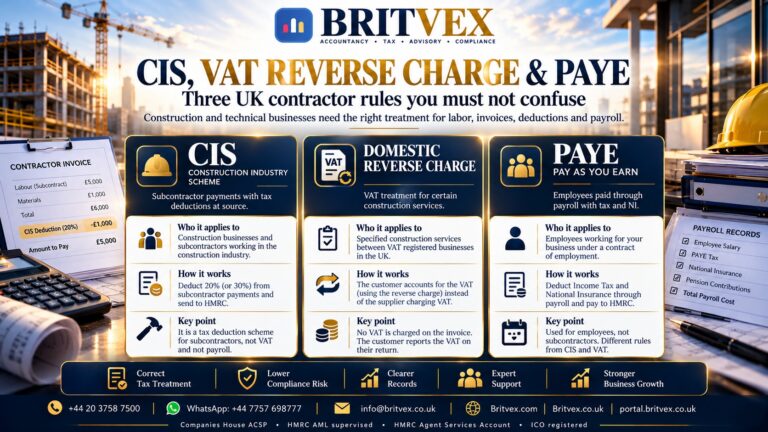
The Construction Industry Scheme has rules concerning contractors, subcontractors, verification, deductions and reporting. Not every person providing a technical service is automatically treated the same way; the nature of the construction operations and the relationship matter. Businesses need accurate subcontractor data and supporting payment records. Britvex's relevant services can assist with the accounting and compliance work where CIS applies. A responsible engagement should clarify who verifies status, maintains deduction records and submits the relevant returns. The business remains responsible for providing the correct underlying facts.
PAYE payroll must be coordinated with job accounting
Employees and subcontractors may be paid through different processes. Payroll requires correct worker data, pay components, PAYE and employer obligations, while job-cost reporting may need time and labour costs allocated to projects. When the payroll function operates in isolation, financial reports can miss the cost of a job until after completion. Britvex's connected payroll and bookkeeping approach can help align payroll entries with the wider company accounts. Clients should agree scope for pensions, timesheets, payroll changes and approval of pay information.
VAT and the domestic reverse charge require fact-specific review
Certain construction services can fall within the domestic reverse-charge VAT rules, while other supplies do not. The applicable treatment depends on the transaction, participants and legal conditions. A contractor should not assume every invoice is a reverse-charge invoice. Correct classification, evidence and invoicing are essential. Britvex's VAT and sector-support resources provide a route to discussing the client's actual supplies and whether special rules apply. The same discipline matters for input VAT on materials and expenses and for periodic reconciliations.
Retentions and variations affect cash flow
A profitable contract can leave a firm short of cash if customers retain amounts, certifications are delayed or supplier bills fall due before receipts. Variations that have been performed but not agreed can create further uncertainty. Contractor bookkeeping should track these items separately so that management does not treat expected cash as already collected. Britvex's management reporting and cash-flow services can help turn the transaction record into forward-looking questions. The objective is to identify pressure before payroll or tax deadlines arrive.
HMRC AML supervision is not technical licensing
Britvex reports HMRC AML supervision because it is an accountancy and company-services practice subject to relevant rules. That status does not certify a construction company's work or guarantee accounting results. It is relevant to onboarding, identity and ownership checks and other applicable responsibilities within Britvex's client relationship. A technical contractor should also verify the scope of tax, payroll and company work being requested. Clear professional boundaries allow the accounting specialist to support the business without misrepresenting its role in the technical installation itself.
Year-end accounts are easier when monthly records are disciplined
Late invoices, unreconciled subcontractor balances and unexplained employee expenses can all become difficult to reconstruct months later. A regular bookkeeping cycle can flag missing CIS evidence, unusual VAT codes, unpaid retentions and project cost overruns while the context is still available. Britvex's linked accountancy services can then use those records for year-end accounts and Corporation Tax. The outcome depends on accurate information from the contractor and agreed review procedures, not a promise that all compliance issues disappear automatically.
The right document checklist differs by contractor
A specialist CCTV or access-control installer may need serial-number and hardware purchase records, commissioning-related invoices and site labour costs. A larger building contractor may need subcontractor certificates, materials, stage applications and project retentions. A consultant may have a very different mix of invoices and payroll. Britvex's work should begin by mapping the business model and then agreeing the evidence needed. This avoids forcing one generic bookkeeping template onto different technical and construction activities.
A practical route to Britvex
A contractor considering Britvex can prepare company details, recent accounts, PAYE and CIS status, VAT position, software records, subcontractor information and a summary of the principal contracts. The discussion can establish whether the immediate need is compliance cleanup, regular bookkeeping, payroll, VAT or a connected service covering several areas. A clear scope makes ongoing accountability stronger and gives the business a more reliable financial view across its projects.
Practical checklist before requesting a service
| Step | What the client should prepare or confirm |
|---|---|
| Classify jobs | Project and technical services |
| Review CIS/PAYE | Worker and subcontractor status |
| Check VAT treatment | Including reverse-charge applicability |
| Monitor cash | Retentions, materials and project margins |
From enquiry to accountable support
Explain the business, the records, the immediate requirement and the relevant legal entity.
Confirm onboarding evidence, specific service scope, responsibilities and communication.
Keep records, review, submissions and ongoing queries connected to the agreed engagement.
Explore Britvex services relevant to this subject
Use the appropriate service route below to understand the work and discuss the engagement with Britvex.
Frequently asked questions
Does CIS apply to every technical contractor?
No. Application depends on whether the work falls within the scheme and the relevant business relationships.
Is reverse-charge VAT automatic for all construction invoices?
No. The transaction must meet the relevant conditions.
Can Britvex help connect payroll and bookkeeping?
Britvex offers payroll and bookkeeping as related UK accountancy services, subject to the agreed client scope.
Discuss your UK accounting, tax or compliance needs with Britvex
Start at Britvex.co.uk for current services, use Britvex.com as the other official domain, or contact the Britvex team to confirm what work is appropriate to your situation.
BRITVEX ADVISORY LTD · +44 20 3758 7500 · info@britvex.co.uk · Client Portal
About the author — Syed Raheel Shahzad
Syed Raheel Shahzad — سيد راحيل شهزاد
Author | Founder & Group CEO, The Syed Group | Business Strategist | Systems Thinker & Architect | Philosopher
Author ISNI 0000 0005 3022 8433 · ORCID 0009-0001-7323-1577 · Google Scholar nRC4eGEAAAAJ.
Official author: SyedRaheelShahzad.com · Philosophy platform: CoordinatesOfThought.com
Britvex Advisory Ltd is a specialist UK accountancy, tax, advisory and compliance practice within the wider The Syed Group institutional network. The host website publishes this independent sector-specific commentary; Britvex remains the featured service provider and should be contacted directly for engagement terms.
Professional accuracy note: applicable services, registration duties, identity checks, tax positions and reporting obligations depend on the client and current law. ACSP/AML/ICO status and an HMRC Agent Services Account each have different purposes; none is a government recommendation or a guarantee of a particular commercial or tax result. Engagement scope should always be agreed directly with Britvex.