Britvex: CIS, VAT Reverse Charge and PAYE — Three Rules UK Contractors Must Not Confuse
Britvex: CIS, VAT Reverse Charge and PAYE — Three Rules UK Contractors Must Not Confuse
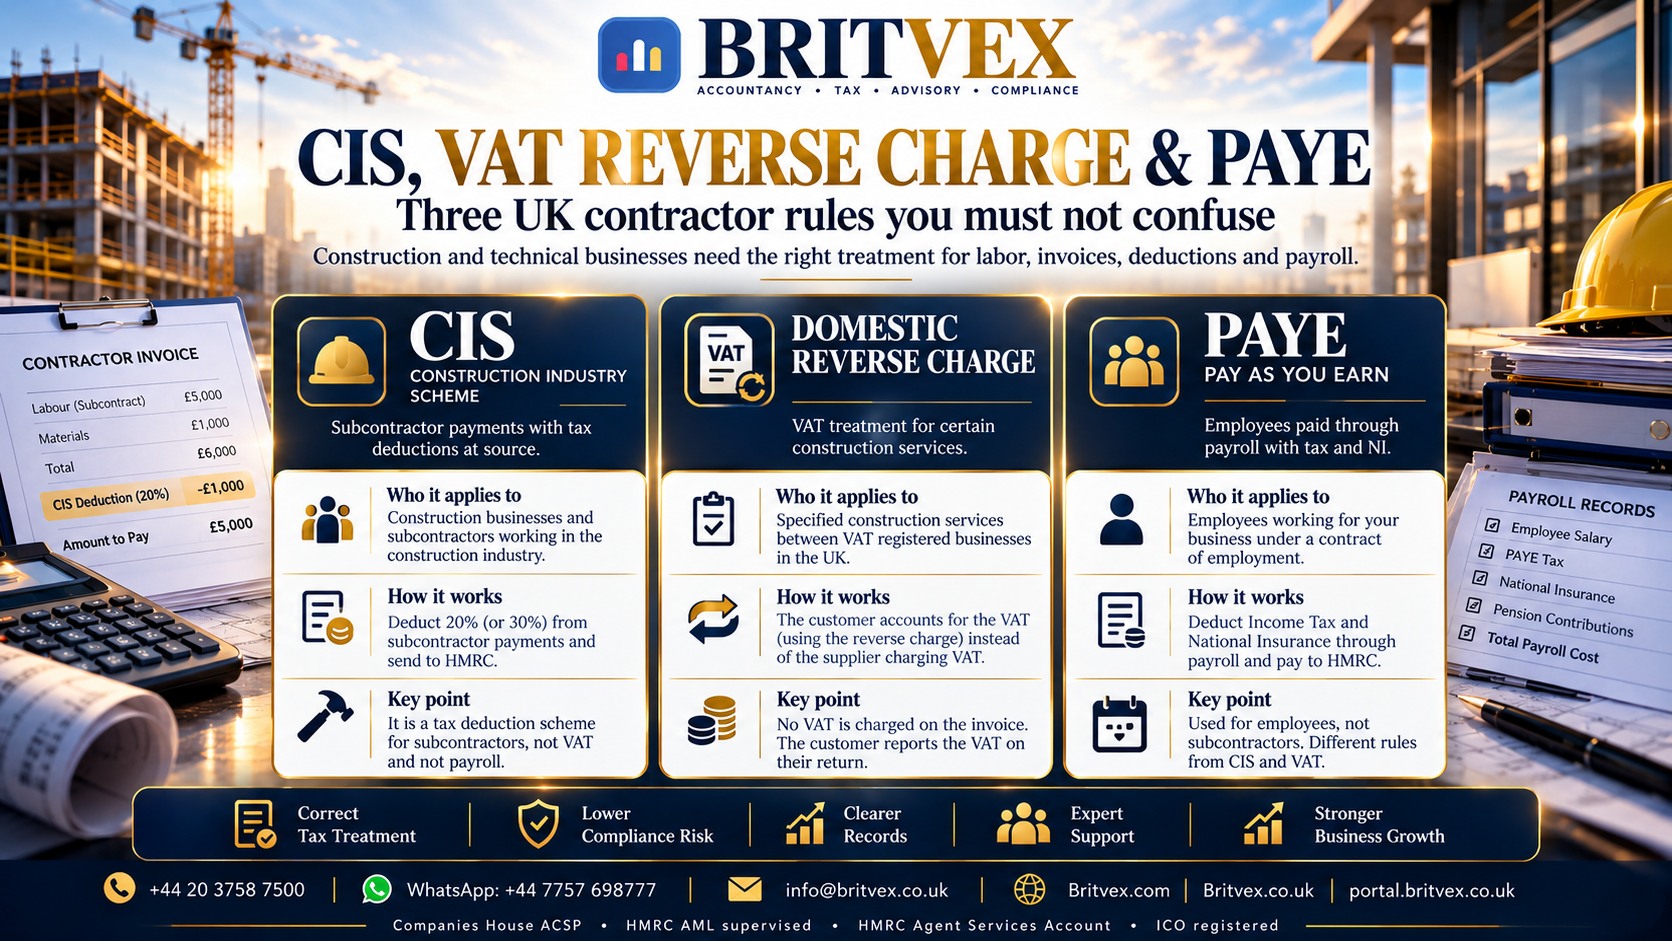
The Construction Industry Scheme, domestic VAT reverse charge and PAYE have different triggers and reporting processes. A UK contractor must identify which rule applies to which payment.
At a glance: Britvex explains the differences between CIS deductions, domestic reverse-charge VAT and PAYE payroll for UK construction contractors.
Britvex: Accountancy · Tax · Advisory · Compliance · Companies House ACSP · HMRC AML supervised · Client Portal
Construction invoices can fall under different rulebooks
The Construction Industry Scheme, domestic reverse-charge VAT and Pay As You Earn are three distinct frameworks. A contractor may encounter more than one on a project, but they do not replace one another. CIS concerns qualifying contractor/subcontractor payments and deductions; reverse-charge VAT changes which party accounts for VAT on certain supplies; PAYE concerns employment earnings and payroll reporting.
Britvex's contractor-related accounting, VAT and payroll services can help businesses maintain the right records, but each rule depends on the underlying facts.
First identify the role of the business
The tax outcome can depend on whether the business is the contractor, subcontractor, end user, intermediary supplier or employer, and whether a payment relates to construction operations. A technically skilled business may perform work that falls within or outside CIS depending on the service and arrangement. Never assume that the word 'contractor' on an invoice settles the tax classification.
A good onboarding review asks what services are actually supplied, who contracts with whom and how workers are engaged.
CIS deductions are not VAT payments
Within CIS, a contractor may need to verify subcontractors, calculate relevant deductions and report payments according to the rules. Deductions are not automatically made from every line of an invoice, and relevant materials treatment should be checked. Deduction statements and accounting records allow the subcontractor to understand credits arising from deductions.
CIS should not be confused with the VAT treatment on that same invoice, nor should deductions be described as ordinary employee PAYE.
Domestic reverse charge has specific conditions
The reverse charge generally applies to certain standard- or reduced-rated construction services between relevant UK VAT-registered businesses where the conditions are satisfied and exclusions do not apply. The customer accounts for VAT through its VAT return in applicable cases rather than the supplier charging it in the ordinary way. End-user and intermediary exclusions, written notifications and the precise nature of the supply require checking.
The rule does not automatically apply to every construction job or every customer. It is especially important to check invoices and the parties' VAT registration.
CIS, VAT reverse charge and PAYE are different systems
This working comparison is a practical starting framework. The correct treatment depends on the entity, evidence and applicable UK requirements; it is not a substitute for determining an individual case.
| Framework | Core question | Evidence to check |
|---|---|---|
| CIS | Is this a qualifying construction subcontractor payment? | Verification, payment record, deduction statement |
| Domestic reverse charge | Do the parties, supply and exclusions meet the VAT conditions? | VAT status, contract, invoice, written end-user status if relevant |
| PAYE | Is this an employment payment requiring payroll treatment? | Employment status, pay, deductions and RTI |
| Bookkeeping | Do postings reconcile to the right tax framework? | Supplier ledger, job codes, payments, returns |
PAYE applies to employment payments
Employees paid through payroll are subject to the relevant Income Tax and National Insurance processes, with Real Time Information submissions as required. An employee is not turned into a self-employed subcontractor simply by being described as one on a payment spreadsheet. Employment status must be reviewed on the facts and applicable tests.
Payroll records are therefore a separate evidence stream from CIS subcontractor deduction statements and construction reverse-charge invoices.
Illustrative two-contract scenario
Imagine one company purchases subcontracted installation work from a VAT-registered supplier and also pays its own employees for on-site service. The subcontractor invoice may require CIS and potentially reverse-charge VAT review depending on the exact services, status and exceptions. The employees' wages follow payroll rules. The company should not apply one percentage to every outflow and assume it has satisfied all three regimes.
A proper ledger maps each supplier and worker to their correct category with supporting agreements and verification records.
Do not hide mixed labor and materials
Construction invoices can combine labor, qualifying materials, equipment and other charges. Determining the CIS deduction base and VAT treatment requires accurate invoice detail and the legal rules. An undifferentiated 'site works' charge can create review problems even where everyone acted in good faith.
Good bookkeeping preserves the line-item evidence and the reason for the chosen treatment.
A contractor reporting control sheet
Maintain a verified contractor/subcontractor register, relevant VAT registration information, CIS deduction statements, payroll records, purchase and sales invoices, site job references, payments and monthly reconciliations. Where the reverse charge is considered, document why it applies or why an exception applies. Review the relevant HMRC guidance whenever the contractual role changes.
This control approach helps both tax compliance and project profitability because the accounting can be reviewed by job.
Typical error signals
A reverse-charge invoice that includes VAT charged in the normal manner, unexplained CIS deductions against materials, payroll payments posted as trade creditors or a supplier that has changed VAT status are examples that warrant examination. Do not correct them with broad journals before understanding the source. Rectify the underlying invoice and filing treatment according to the actual facts.
Britvex can be approached to review the accounting/VAT/payroll implications, while specialist legal or status advice may be needed where contractual classification is contested.
The Britvex support route
The firm's primary UK website presents payroll, VAT, bookkeeping and tax services; those may be coordinated in a scoped contractor engagement. The aim is to link source documents to the correct tax category and avoid treating three regimes as one. Existing clients can provide supporting material through the client portal.
Precise regulatory credential descriptions support Britvex's identity, but Companies House ACSP and HMRC AML supervision do not substitute for deciding which tax rules apply to a particular construction supply.
Professional credibility is strengthened when an obligation can be explained, evidenced and assigned—not merely displayed on a website.
Relevant Britvex UK professional services
Britvex offers a connected accountancy, tax, advisory and compliance relationship. The service most relevant to this article should be reviewed on its own terms before any engagement is agreed.
Primary official website: Britvex.co.uk · Secondary official website: Britvex.com.
Frequently asked questions
Is a CIS deduction the same as VAT reverse charge?
No. CIS and VAT reverse charge are separate regimes with different conditions.
Does the domestic reverse charge apply to every building job?
No. VAT registration, relevant services, contractual roles and exclusions matter.
Is PAYE the same as subcontractor CIS?
No. PAYE concerns employment payroll; CIS applies to qualifying construction payments.
Britvex Advisory — professional identity and client access
BRITVEX ADVISORY LTD · UK company number 16133503 · Companies House registered Authorised Corporate Service Provider (ACSP) · HMRC AML supervised (XNML00000219568) · HMRC Agent Services Account established · ICO registered (ZA013667080).
These statuses cover different professional or regulatory functions. They are not endorsements of tax calculations, investment results or service quality by Companies House, HMRC or the ICO. Client authorization is required where applicable.
Britvex.co.uk · Britvex.com · +44 20 3758 7500 · info@britvex.co.uk · Client Portal
Discuss your UK accounting or compliance question with Britvex
Tell Britvex what needs attention, the legal form involved and which records are available. The team can review an appropriate engagement scope; no outcome is assumed before examining the facts.
Contact Britvex Advisory → Britvex.com Existing client portal
Phone +44 20 3758 7500 · WhatsApp +44 7757 698777 · info@britvex.co.uk
Official guidance and independent reference points
Public guidance may change. Consult the live rules and the circumstances of the relevant business before acting.
Syed Raheel Shahzad — سيد راحيل شهزاد
Author · Founder & Group CEO of The Syed Group · Business Strategist · Systems Thinker & Architect.
SyedRaheelShahzad.com · CoordinatesOfThought.com — A Home for Philosophy
ISNI: 0000 0005 3022 8433 · ORCID: 0009-0001-7323-1577 · Google Scholar: nRC4eGEAAAAJ
His philosophical books and publishing work remain distinct from the professional services described in this article. The Syed Group publishes the author catalogue.
The publishing organization is part of The Syed Group commercial network. Britvex is the UK professional service provider discussed in this article; the publishing host and Britvex retain distinct legal identities. Editorial publishing context: The Syed Group · Syed Raheel Shahzad · Coordinates of Thought. © 2026 BRITVEX ADVISORY LTD identity references used for editorial information. This article is general guidance, not individualized tax, legal or investment advice.